
A house alongside the Fox River is surrounded by floodwaters, close to Crystal Lake, Illinois, April 21, 2026.
Scott Olson | Getty Pictures
Many owners have a giant hole of their insurance coverage protection — and so they doubtless do not know it, in accordance with insurance coverage consultants.
That leaves policyholders financially uncovered to break, together with from pure disasters which can be changing into extra frequent or expensive, corresponding to wildfires, hurricanes and flooding — doubtlessly placing their largest monetary asset in danger, consultants mentioned.
Prices for customers to maintain their protection have risen considerably lately amid hovering insurance coverage premiums.
“A supermajority of householders wish to totally and adequately insure their houses, are keen to pay for it, and suppose they’ve it,” Kenneth Klein, a legislation professor at California Western College of Regulation, wrote this yr in a Lewis & Clark Regulation Evaluation article. “However most of them are mistaken and are brief by so much.”
A ‘disaster of underinsurance’
A burned neighborhood within the aftermath of the Marshall wildfire, Louisville, Colorado, Jan. 24, 2022.
Kent Raney | Istock | Getty Pictures
About 90% of owner-occupied houses within the U.S. are insured, Klein wrote.
The standard householders insurance coverage coverage places monetary limits on protection in a wide range of methods — for instance, by excluding sure sorts of disasters or capping payouts for sure objects or sorts of injury.
Klein carried out an evaluation of California Division of Insurance coverage knowledge on 74,000 fire-related claims of any dimension — from wildfires to deal with fires — from 2018 to 2023. Amongst these claims, greater than 70% of householders with insurance coverage had been underinsured by a median of roughly 20%, Klein wrote.
The issue just isn’t restricted to California, he mentioned.
“This knowledge reveals that there’s a barely hidden nationwide disaster of underinsurance,” Klein wrote. The dynamic “persistently and inevitably robs householders of any probability to completely recuperate what they’ve misplaced,” he wrote.
There are various the reason why householders are underinsured, consultants mentioned.
Some customers could deliberately select a lesser protection quantity simply to afford any protection in any respect, Amy Bach, co-founder of United Policyholders, a client advocacy group, wrote in an e-mail.
Nonetheless, many customers are unaware of the hole, consultants mentioned.
On one hand, a “broad swath” of Individuals do not perceive what they’re shopping for on account of complicated language of their insurance coverage contracts, in accordance with analysis printed in Might in Virginia Regulation Evaluation.

Moreover, insurers proceed to exclude extra issues from protection and cap the greenback quantities for the issues they do cowl, Bach wrote.
Shoppers additionally typically underestimate how a lot it might price them to rebuild their houses, consultants mentioned.
Sadly, “protection gaps are sometimes found on the time of the loss — which is when you do not wish to uncover them,” mentioned Lareesa Klingler, director of nationwide claims for the personal threat options group of Lockton, an insurance coverage brokerage.
Listed here are a few of customers’ largest insurance coverage gaps, in accordance with consultants.
1. Flooding
A neighborhood that flooded after the failure of a short lived flood barrier alongside the White River, in Pacific, Washington, Dec. 16, 2025.
David Ryder | Reuters
The standard householders insurance coverage coverage excludes or limits protection for injury from sure disasters, corresponding to earthquakes, landslides and floods, in accordance with insurance coverage consultants.
However customers most frequently get tripped up by the latter — and it may be expensive, in accordance with insurance coverage consultants.
Householders want separate insurance coverage to cowl bodily injury attributable to a flood, outlined as water coming into a house from the bottom up. Which will happen on account of storm surge, heavy rainfall or an overflowed physique of water corresponding to a lake or river.
Flooding is the most typical and expensive pure catastrophe within the U.S., in accordance with the Insurance coverage Data Institute.
Only one inch of water could cause about $25,000 of harm to a home-owner’s property, in accordance with the Federal Emergency Administration Company. Between 2020 and 2024, the typical fee for all flood claims was $82,614, in accordance with FEMA.
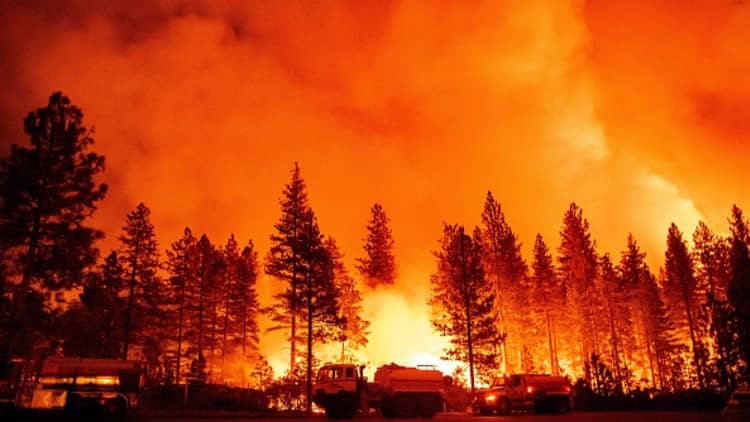
And flood insurance coverage is not simply for many who dwell close to the water: About 99% of U.S. counties have skilled a flood up to now 20 years, in accordance with FEMA’s floodsmart.gov.
However a 2025 weblog submit from the company signifies lower than 4% of U.S. households have purchased a coverage from the Nationwide Flood Insurance coverage Program.
NFIP is the first supply of flood insurance coverage protection for residential properties.
A typical householders insurance coverage coverage does cowl sure water injury: For instance, in situations of “wind-driven rain,” primarily when water will get into the home from the highest down, consultants mentioned.
This may occur if a hurricane damages a roof, and rain will get inside and soaks your entire home or a number of rooms, consultants mentioned.
Insurers could exclude or cap advantages for mildew injury, although, Bach mentioned. They could additionally cap payouts for water injury at maybe $5,000, $10,000 or $15,000 per loss, she mentioned.
California Insurance coverage Commissioner Ricardo Lara this week urged customers to overview their protection and think about flood insurance coverage forward of a possible historic El Niño. Folks should not wait till a catastrophe is approaching, Lara mentioned: Flood insurance coverage typically takes impact 30 days after buy.
Even with flood insurance coverage, there are caveats. For instance, conventional insurance policies sometimes limit protection for basements.
2. Rebuilding prices
New houses being constructed on cleared heaps the place houses had been destroyed by the Eaton Fireplace, Altadena, California, Sept. 17, 2026.
Mario Tama | Getty Pictures
Underestimating the price of rebuilding is one other huge supply of underinsurance, mentioned Peter Kochenburger, visiting legislation professor at Southern College Regulation Heart and managing fellow of its Insurance coverage Regulation and Coverage Institute.
“The price of constructing and repairing has gone manner up,” Kochenburger mentioned. “When you lose the home and the bounds of your householders coverage aren’t adequate to rebuild, you are kind of caught until you will have your personal monetary property — which many individuals do not.”
Alternative prices for property-and-casualty-related losses elevated by 45% between 2020 and 2023, on common, in accordance with a Treasury Division report printed final yr. Householders insurance coverage is a kind of property and casualty insurance coverage, as are renters insurance coverage and auto insurance coverage.
A supermajority of householders wish to totally and adequately insure their houses, are keen to pay for it, and suppose they’ve it. However most of them are mistaken and are brief by so much.
Kenneth Klein
legislation professor at California Western College of Regulation
Labor prices have elevated, too. The price of using staff constructing single-family houses jumped 37% between 2018 and 2022 and 45% from 2014 to 2023, the report mentioned.
Shoppers can think about shopping for “prolonged substitute price” protection, an add-on to a standard insurance coverage coverage, mentioned Klingler, of Lockton.
This typically tacks on an extra 10% to 50% above a client’s restrict for dwelling protection, which is the utmost a coverage pays to rebuild a house from the bottom up, in accordance with Policygenius, an insurance coverage comparability web site.
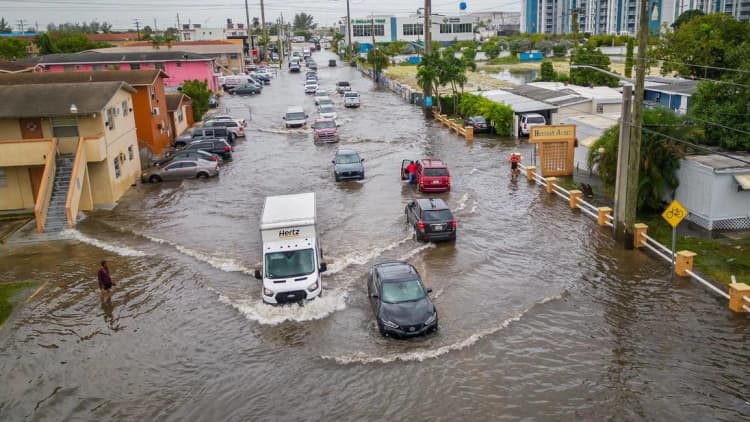
Shoppers — particularly these with older houses — also can think about shopping for one thing known as “ordinance or legislation protection,” Klingler mentioned.
This protects in opposition to greater prices that come up from the necessity to convey a house as much as present constructing code — corresponding to upgrades to wiring, plumbing or insulation — when rebuilding.
3. Limits on particular objects
Peter Dazeley | Photodisc | Getty Pictures
Insurers generally restrict the sum of money they pay for a lot of classes of particular contents, which can embody paintings, collectibles, rugs, furs and different costly objects, consultants mentioned.
Nonetheless, customers should buy add-ons to a standard coverage to boost the greenback limits for these particular person objects.
“If individuals have antiques or weapons or electronics or jewellery or these sorts of particular objects, they should confirm how these are lined, and whether or not [they] want extra protection for these objects,” mentioned Brenda Cude, professor emeritus of economic planning, housing and client economics on the College of Georgia and a client consultant on the Nationwide Affiliation of Insurance coverage Commissioners.