
shapecharge/E+ through Getty Photographs
AI and Curiosity Fee Threat
Letter Abstract
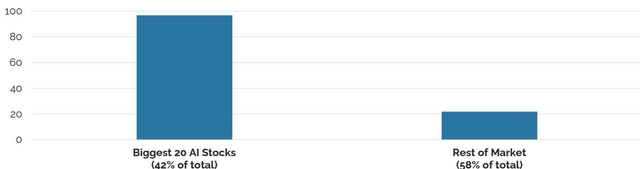
Over the previous three years, the market worth of all shares with free money stream knowledge within the Russell 1000 Index has elevated by $32 trillion towards a achieve of $400 billion in estimated free money flows (NTM FCF). The overwhelming majority of the market cap improve was pushed by the largest 20 Synthetic Intelligence (AI) shares, which grew by $20 trillion regardless of their NTM FCF staying basically flat. With these 20 AI shares now making up over 40% of the index and buying and selling close to 100x NTM FCF, there’s a notable focus and valuation danger the place the precedents recommend warning is warranted (See Determine 1 beneath & Desk 1 within the appendix). The opposite ~860 shares, representing 60% of the market, noticed fairly wholesome free money stream progress and extra commensurate market cap positive aspects such that valuation multiples expanded solely barely. Inside that group, there stays a variety of very enticing funding alternatives, although monetary leverage and the sustainability of the underlying outcomes must be thought-about. Indebtedness is of specific concern at current given rising charges. Whereas greater bond yields pose a danger to fundamentals, particularly amongst extra leveraged smaller corporations, the a lot larger menace is that if they trigger fairness multiples to contract from traditionally elevated ranges. Total, this market backdrop appears to be like remarkably much like the final know-how increase. Then as now, regardless of costly total market valuations, there was a big group of attractively valued shares that went on to carry out very effectively even by broader market turbulence that ensued put up the increase’s peak. Every market episode of word can be completely different in vital methods. The present AI increase is bigger than previous new-tech cycles, the guarantees of the brand new tech are completely different, and the threats to current enterprise fashions and know-how are completely different. Amid this setting, we stay targeted on the economics, with our holdings throughout methods pushed by enterprise stability, the avoidance of extra leverage, and the data that higher valuations ought to in the end drive higher returns over time.
Efficiency Abstract*
U.S. Elementary Stability & Worth (U.S. FSV): Our U.S. FSV technique’s internet of payment return of 9.39% YTD lagged the S&P 500’s achieve of 12.73% and the Russell 1000 Worth’s 19.23% achieve. Annualized internet of payment efficiency since inception is now 1.05% behind that of the S&P 500 and a pair of.82% forward of the Russell 1000 Worth Index.
U.S. Small/Mid Cap High quality & Worth (SMID QV): Our SMID QV technique returned 18.46% YTD, internet of charges, which compares to the Russell 2000 index’s whole return of 13.87% and the Russell 2000 Worth’s 17.22%. Annualized extra returns of our SMID QV since inception are 4.04% and three.75% forward of these benchmarks, respectively.
Worldwide Elementary Stability & Worth (Intl. FSV): Our 8.57% YTD return after charges lags the MSCI All Nation Ex US ETF benchmark’s achieve of 13.85% and annualized internet of payment efficiency since inception stays barely forward of that benchmark.
Lengthy/Brief Fairness (previously US Worth 130/30): Our Lengthy/Brief technique returned 20.92% YTD vs. the S&P 500 Index’s return of 12.73%. This technique is 2.36% forward of the S&P 500 Index and 6.11% above the Russell 1000 Worth Index annualized, internet, since inception.
U.S. Free Money Move 500: Our broader free-cash-flow-weighted portfolio returned 15.83% YTD vs. 12.73% for the S&P 500 and is forward of that benchmark since inception, internet of charges, by about 1% annualized.
Fig 1: Market Cap to NTM FCF A number of for Largest 20 AI Shares vs. the Remainder of the Market (Russell 1000)
Market Replace:
In July and August of Q3 ’26, AI and momentum shares (largely one and the identical) rolled over solely to bounce again in September. The transfer might be seen within the tail finish of Determine 2 which compares the S&P 500 Momentum Index vs. the typical inventory as measured by the S&P 500 Equal Weight Index. Whereas these adjustments felt monumental to many market contributors experiencing them, they’re small in a longer-term context, and as you will word, comparable strikes occurred within the late Nineties.
Momentum weakened in July and August and recovered in September, however nonetheless appears to be like troublingly just like the late Nineties.
Determine 2: S&P 500 Momentum vs. 500 Equal Weight

Supply: FactSet. 9/30/2026. Complete return indexes. Momentum index begins in 1995.
Semiconductor shares adopted the identical sample within the quarter. Determine 3 plots their worth as a share of world Gross Home Product (GDP), emphasizing the purpose from the introduction that whereas a lot of at present’s setting parallels that of late Nineties, the size is now a lot bigger. U.S. semi shares are actually almost 2x as massive a share of worldwide financial exercise as they have been throughout the web bubble.
The worth of U.S. semiconductor shares is greater than twice as large a share of world GDP because it was within the Nineties know-how increase.
Determine 3: Worth of Semiconductor Shares within the Russell 1000 Index as a Share of World GDP

Supply: FactSet, IMF, knowledge as of 9/30/2026.
Inventory worth will increase are far exceeding positive aspects in financial exercise.
Determine 4: Three-12 months Change in S&P 500 Market Cap vs. GDP (Trillion)

Supply: FactSet, Bureau of Financial Evaluation, knowledge as of Sept ’26 with GDP estimate.
Stepping again, whereas the $30 trillion improve in market cap for U.S. shares within the final three years is exceptional in an absolute sense, it’s much more anomalous when scaled towards financial output (GDP). Determine 4 plots the rolling 3-year change in U.S. GDP versus the market. The 2 typically transfer in line as higher financial progress results in stronger free money stream progress and thus a much bigger market valuation, however there are occasions when the 2 disconnected as occurred within the late Nineties and once more extra not too long ago.
To match the 3-year change in market cap progress vs. GDP extra instantly, Determine 5 reveals the 2 as a ratio and excludes damaging durations like 2020 when weak or damaging GDP progress causes nonsensical numbers. The ensuing plot reveals that market cap positive aspects and GDP progress have typically tracked intently or reverted to long-term averages. The interval of the Nineties stands out when the 3-year market worth improve was round ~4x larger than the rise in GDP. However even that interval was eclipsed by the market cap improve over the newest 3 years which exceeded the rise in GDP by over 6x.
Over 3-year durations, the rise within the whole worth of S&P 500 shares tends to match the change in GDP, however the two diverged within the Nineties & at present.
Determine 5: Ratio of 3-12 months Market Cap Change to GDP

Supply: FactSet, Bureau of Financial Evaluation, knowledge as of Sept ’26 with GDP estimate.
Because of the inventory market rising rather more quickly than GDP, the ratio between the 2 (a metric favored by Warren Buffett and typically known as the “Buffett Indicator”) is at a report peak. Determine 6 depicts this measure and once more highlights how the present market differs from the one within the late Nineties in its scale.
The market worth of the S&P 500 as a share of U.S. GDP, often called the “Buffett Indicator” is at a report peak.
Determine 6: S&P 500 Market Worth as a Share of U.S. GDP

Supply: FactSet, Bureau of Financial Evaluation, knowledge as of Sept ’26 with GDP estimate.
The counterargument to the Buffett Indicator is that it compares the valuation of U.S. corporations with massive abroad earnings to home and never world GDP. One other legitimate level of competition is that it ignores profitability and so misses valuation and the likelihood {that a} market’s whole price in relation to GDP is excessive as a result of so are its earnings. Determine 7 beneath responds to those issues and plots the S&P 500 in combination towards world GDP. The whole ratio is decrease given a a lot bigger determine that’s world GDP, however the normal pattern is analogous. The road on the chart’s proper axis reveals the free money a number of for the market on a trailing foundation and demonstrates that a lot of the variability out there worth to GDP line is because of valuation swings and never profitability. Profitability does, nevertheless, clarify a few of the current transfer as the present a number of is beneath the 2000 peak regardless that the market worth to GDP is greater.
U.S. equities are additionally at a peak as a share of world GDP with the valuation a number of of free money driving a lot of the change.
Determine 7: U.S. Mkt Cap to International GDP vs. FCF A number of

Supply: FactSet, IMF, knowledge as of Sept ’26 with GDP estimate.
AI Threat & How the Market Gained $30 Trillion in 3 Years:
We’re rising weary of discussing the AI commerce considerably repeatedly within the final a number of letters. That mentioned, the figures aren’t these of a typical market cycle they usually eat our time as the end result will seemingly show related to inventory returns for the following decade or longer. In that context, much more exceptional than the truth that the market gained $30 trillion in worth in three years is the focus of that achieve. Simply the 20 greatest AI-stocks accounted for $20 trillion of the $30 trillion of progress with Apple (AAPL) including one other $2 trillion to that determine.
Extra exceptional nonetheless, the group of 20 AI shares noticed nearly no improve in NTM FCF regardless of a $20 trillion market cap achieve. A few of these corporations, like NVIDIA (NVDA), have seen extraordinary free money stream progress, however the positive aspects of NVIDIA and others largely got here out of the earnings of different corporations within the group such that the mixture free money stream determine for all 20 shares was little modified. Because the hyperscalers (Alphabet (GOOGL), Amazon (AMZN), Meta (META), Microsoft (MSFT), Oracle (ORCL), and SpaceX (SPCX)) ramped up spending and noticed their free money flows collapse, earnings rose for the beneficiaries of that funding like NVDIA. Desk 1 on the finish of the letter highlights this within the two rows beneath the “AI 20” row by exhibiting that the hyperscalers noticed a lower in FCF of round $450 billion, whereas the opposite 14 corporations noticed a rise of an identical quantity.
The shift is sort of clearly the results of the unprecedented funding spending of the hyperscalers. Determine 8 reveals the funding simply from these six corporations as a share of GDP after which compares that determine to the typical and peak annual figures from prior funding booms. The spending from simply these 6 corporations has already far exceeded the typical ranges of all different funding booms within the historical past of the U.S. and the height yr for every episode save the railway increase in 1870. Additionally it is notable and considerably worrying that the asset lives in these booms have been typically for much longer than at present (i.e. railway observe last more than GPUs).
The present funding increase is traditionally unprecedented
Determine 8: Hyperscaler Funding as a Share of GDP vs. Prior Funding Booms

Supply: FactSet, knowledge as of Sept 2026. Consists of AMZN, GOOGL, META, MSFT, ORCL, SPCX. Historic knowledge from “Financing the AI Buildout” (Van Nieuwerburgh 2026)
The unprecedented degree of funding spending will sooner or later want to provide equally unprecedented degree of revenues and earnings to show it a smart enterprise. A wide range of current estimates recommend that to earn a modest 10% return on AI capital expenditures, whole AI revenues might must be within the $3 trillion vary on an annual foundation by 2030 (Bernstein & Cummings $2.4T, Van Nieuwerburgh $2.7T, Goldman Sachs $3T, Bain $6T). To get a way of scale, these figures equate to ~$7k to $17k per individual within the U.S., or ~$35k to $85k per yr for a household of 5. In actuality, a few of the anticipated revenues would come from exterior the U.S., however the magnitude of the mandatory spending stays monumental.
Along with the sheer scale, there are quite a few and really important challenges to reaching these estimates. Securing the facility to run the deliberate knowledge facilities and developing them on time and on finances is not any simple feat given their complexity. Towards a backdrop of round 16 gigawatts (GW) of operational capability within the U.S. as of August, solely half of the deliberate 26 GW of latest capability for 2026 has even begun development, in line with the consultancy Currence. For 2027, solely 10 GW are underneath development out of 55 GW deliberate for supply. With development requiring round 2-3 years, it’s clearly unlikely that a lot of this capability will likely be delivered.
Funding is one other important problem. Regardless of having very worthwhile companies exterior of their AI ambitions, hyperscaler spending is so massive that it’s now effectively eclipsing working money flows and free money flows are damaging a whole bunch of billions of {dollars} after incorporating the price of fairness issuance. Whilst capital expenditures are anticipated to degree off at round $1.3 to $1.4 trillion, the group is just not anticipated turn into free money stream constructive till 2029 (See Determine 9). And constructive FCF then solely comes after a projected almost 150% improve or $1T rise in money from operations from an already very massive $700 B start line. Present damaging money flows and the unbelievable price of AI funding clarify why almost $500B of AI -related debt has been issued this yr by September in line with the Financial institution of England. It additionally addresses why Alphabet issued ~$85 in fairness, and why SpaceX tapped credit score markets for $40B solely months after getting $80B from its preliminary public providing (IPO).
Hyperscaler free money flows are projected to be damaging till 2029.
Determine 9: Hyperscaler Money Flows (Billion)

Supply: FactSet, knowledge as of Sept 2026. Money stream put up worker inventory comp which grows 10% per yr in 2026-2029E Consists of AMZN, GOOGL, META, MSFT, ORCL, & SPCX.
Hyperscaler funding is just not the one problem because it have to be thought-about alongside the financing wants of the frontier labs (OpenAI (OPENAI) and Anthropic (ANTHRO)) as their funding sources and companies are closely intertwined. OpenAI not too long ago signaled that it expects a virtually $300B cumulative working loss from 2026 by 2030, and it will must be financed from someplace. OpenAI is consequently reported to be negotiating Center Japanese financing of $30B, shortly on the heels of its $122B funding spherical in February. The anchor of that February funding was Softbank (SFTBY), who’s likewise now searching for funding within the Center East, in search of $100B to cowl its investments in AI and OpenAI particularly. Along with Softbank, the hyperscalers have been main financiers of the frontier labs who in return have pledged to spend effectively over $1T on compute and infrastructure largely with the hyperscalers. This round financing and massive interdependency is much like the “vendor financing” that occurred within the final tech increase. It additionally entails the semi corporations like NVIDIA and Broadcom (AVGO) that are equally investing of their clients and offering debt ensures to assist purchases from the hyperscalers and neoclouds (smaller datacenter builders like Coreweave (CRWV) and Nebius (NBIS)). Credit score to this point is flowing however the quantity wanted will develop considerably subsequent yr.
The largest potential obstacle to the extent of required AI profitability is rather more easy in our view—the trade appears to be like extraordinarily aggressive and switching prices are low. The frontier labs are actually preventing for share on value however are additionally going through steep competitors from low-cost open-source fashions. There’s additionally the likelihood that the know-how will evolve and enhance on a price and effectivity foundation such that many makes use of may in the end be accomplished on native gadgets, or “on edge”, which could negate the necessity for a lot of the info heart capability that’s projected. New forms of fashions like Jev, which features as a really low-cost resolution or routing mannequin, may additionally introduce competitors and threaten required future earnings.
All of that is eerily much like the infrastructure buildout that accompanied the tech bubble within the Nineties. The web and the tech demand associated to it ended up far exceeding even essentially the most optimistic expectations, however the distribution and degree of earnings nonetheless upset and fairness traders took a extreme beating. We aren’t AI skeptics and consider that much like then, shoppers and corporations past these financing the buildout might find yourself once more as the best beneficiaries. It could be extra seemingly {that a} well being care or industrial firm makes use of AI to cut back prices and improve earnings than it’s that the hyperscalers and frontier labs will generate trillions in new annual income in a couple of years’ time.
There’ll undoubtedly be surprising outcomes alongside the way in which, however a subjective evaluation of the problems appears supportive of the target outcomes pushed by valuations and stability sheet concerns that depart us with little publicity to the group.
Rising Charges
After falling for a stretch of roughly 40 years, bond yields are actually rising. The components behind this embody cussed inflation, elevated authorities debt and deficits, diminished demand for developed market bonds from higher-saving rising markets like China, and a crowding out impact from the big issuance of company debt associated to AI. Relating to the latter, Michael Cembalest at JPMorgan (JPM) not too long ago famous that debt issuance by the hyperscalers and NVIDIA is equal to 35% of long-term U.S. Treasury issuance. The mixed result’s that rates of interest are rising and doing so globally (See Determine 10).
International bond yields are rising sharply after a 40-year downtrend.
Determine 10: Developed Market Bond Yields

Supply: FactSet, knowledge by Sept ’26
Rising charges pose two dangers to shares. First, they may seemingly negatively impression fundamentals each instantly by elevating company curiosity prices and not directly by weakening financial exercise. The second, bigger and extra regarding problem is whether or not rising bond yields would possibly trigger fairness multiples to contract as mounted revenue alternate options turn into extra enticing. Usually, fairness yields and bond yields transfer in an identical sample. Utilizing the NTM FCF yield on the S&P 500 (which begins round 2010 when ahead estimate turned broadly accessible) this was true for many of the previous decade as shares and BAA-rated bonds traded almost in lockstep. However as optimism round AI took maintain, the 2 diverged sharply (See Determine 11).
The fairness FCF yield and BAA bond yield have diverged sharply.
Determine 11: Fairness NTM FCF Yield vs. BAA Bond Yield

Supply: FactSet, knowledge by Sept ’26
Taking a look at an alternate longer-term measure of relative valuations utilizing trailing fairness free money stream yields, Determine 12 reveals the place present valuations rank versus historical past. Treasury bonds are above their common going again to after we first have trailing free money stream knowledge in 1985. BAA bond yields are presently close to their common and actual property free money stream yields based mostly on cap charges are solely barely beneath their common. Equities, nevertheless, stand out as being very wealthy by historic requirements with present FCF yields effectively beneath their historic vary. It isn’t unrealistic to suppose that that greater bond yields, waning enthusiasm for AI, or a mixture of the 2 may trigger fairness yields to retether to their historic averages and re-synch with valuations for various asset lessons. Even when fairness valuations solely transfer a part of the way in which, the draw back danger for the market could possibly be substantial.
Equities stand out as costly vs. historical past in comparison with different belongings.
Determine 12: Present vs. Historic Vary of Asset Yields

Supply: FactSet, Normal & Poor’s 9/30/2026
We keep away from corporations with excessive leverage and those who commit a good portion of their working money flows to curiosity expense. We thus keep away from to a point the impression of refinancing in the next price setting and the revenue strain that probably performs although. It is a a lot bigger danger for small corporations however is a matter we keep away from in all of our methods. The larger danger to shares is valuation. However right here too, the free money multiples on the shares we personal are typically a fraction of the general market a number of, probably offering insulation from a number of compression. These components have been at play throughout the unwinding of the Nineties tech increase and resulted in monumental divergence in efficiency of value-based methods on the time.
Whereas imply reversion is a robust drive in markets, it’s attainable that fairness multiples will keep at elevated ranges regardless of rising bond yields. Additionally it is attainable that AI corporations will quickly be producing the trillions of latest income wanted to justify their funding spending and that annual hyperscaler working money flows will likely be $1T greater than at present. However this situation is basically what’s priced into markets at present, and the draw back danger if these outcomes don’t materialize appears to be like probably important.
Technique Updates
U.S. Massive Cap Technique
Valuation appears to be like to be a key danger at current with each the S&P 500 and Russell 1000 Worth benchmarks buying and selling at very wealthy ranges. Since that is pushed by a small handful of very massive and really costly names, there stays a big variety of very attractively valued shares accessible to us out there. The result’s an awfully large divergence within the valuation of our portfolio versus its benchmarks (See Determine 13).
Distillate’s U.S. FSV is considerably cheaper than its benchmarks.
Determine 13: Free Money (NTM) to Market Cap Yield for Distillate’s U.S. FSV Technique vs. Benchmarks

Supply: FactSet. Knowledge by 9/30/2026. FCF yield after possibility issuance.
We stay targeted on fundamentals. A lot of the market’s return has come from valuation growth and never basic progress and that is true for each the broader S&P 500 and Russell 1000 Worth Index. Whereas a number of growth (and contraction) could cause costs and fundamentals to diverge over stretches of years, over the long-term fundamentals are the one diver of returns (see our 1Q 2026 letter for a historic evaluation). Our concentrate on the consistency of money technology after which methodically rotating out of shares whose valuations have elevated, shopping for as a substitute what’s newly low-cost the place every greenback invested buys extra underlying free money stream. This final result of our portfolio development course of is designed to develop the underlying free money stream of our technique at a price effectively above that of each the S&P 500 and Russell 1000 Worth (See Determine 14). Whereas reaching this objective can nonetheless end in moments the place our methods lag their benchmarks if these indexes are seeing valuation growth, we in the end consider it’s the proper strategy and one that’s sustainable and the outcomes replicable, even in a market the place total valuations are receding.
On this regard, going again to the primary full yr for which our U.S. FSV technique’s fundamentals have been accessible, and utilizing consensus estimates for 2026, this design has not simply produced higher free money stream progress, however higher efficiency on a large variety of basic measures as seen in Determine 14. We’ve got lagged nevertheless, on value. Stated otherwise, whereas the general return of our technique has saved tempo with the S&P 500, the shares we personal have turn into cheaper over time whereas the S&P 500 has turn into considerably costlier.
Figuring out valuation growth is often adopted by durations of contraction, the timing of which is inconceivable to foretell, we’re happy that our returns depend on the basics.
Elementary positive aspects for our U.S. FSV technique has been strong.
Determine 14: Elementary & Value Progress ’18 to ’26E for Distillate’s U.S. FSV Technique vs. Benchmarks

Supply: FactSet, knowledge as of Sept ’26
One other usually neglected or misunderstood part of free money stream progress for our methods is valuation itself. Shares which might be cheap on a free money stream foundation can use that money to assist progress by acquisitions or share repurchases. The homebuilder Toll Brothers (TOL) presents a helpful instance. The corporate has confronted challenges over the previous decade with a extra sluggish housing market and gross sales progress has consequently annualized at a mid-single digit price. Over this time, the inventory constantly traded at a double-digit free money stream yield and has steadily used its money technology to cut back its share rely. Due to this, the corporate’s extra modest positive aspects in market cap, gross sales, and free money stream have been magnified into excellent efficiency on a per share foundation and have translated into comparable robust positive aspects for its shares (See Determine 15).
Attributable to a 50% discount in its share rely owing to an inexpensive valuation, Toll Brothers fundamentals on a per share foundation have been glorious.
Determine 15: Toll Brothers ’17 to ’27E Progress

Supply: FactSet. Knowledge as of 10/9/2026. Mkt cap & inventory value for ’26E & ’27E are present values, all others consensus estimates.
U.S. Small/Mid Cap Technique
Amid worries about focus and AI publicity for big U.S. shares, small U.S. shares appear like a really enticing various. Monetary leverage and lack of money stream, nevertheless, are key dangers that must be thought-about. That is evident within the side-by-side charts in Determine 16 exhibiting leverage for numerous benchmarks and our technique together with the share of every portfolio by weight that isn’t anticipated to generate constructive free money flows.
Many small cap shares have important debt and are unprofitable.
Determine 16: High quality Measures for Small Shares

Supply: FactSet, knowledge as of Sept ’26
These points trigger us to favor the higher-quality S&P 600 benchmark as valuation gauge for small shares. Small shares are actually extra enticing than the S&P 500 after being richer for a lot of the previous decade and subsequently underperforming (See Determine 17). Our technique, which has even much less leverage, is considerably extra attractively valued than even the S&P 600, with a free money to market cap yield of just about 11%.
Small shares look extra interesting on valuation.
Determine 17: Distillate’s Small/Mid QV Free Money to EV Yield vs. Key Benchmarks

Supply: FactSet. Knowledge by 9/30/2026. FCF yield after possibility issuance.
Stepping again, worth as a method and when measured using free money stream, has labored very effectively within the small cap universe regardless that there are moments when it lags. Determine 18 highlights this by exhibiting the efficiency of every quintile of valuation on our free money stream
methodology with quarterly rebalancing. Our small technique goals to seize this long-term alternative whereas additionally incorporating high quality to attenuate draw back dangers.
Cheaper quintiles of small shares on FCF have outperformed traditionally.
Determine 18: Russell 2000 Efficiency by FCF/EV

Supply: FactSet. Excludes finance/rental/leasing, monetary conflomerates, funding banks/brokers, life/medical health insurance, main banks, multi-line insurance coverage, P&C insurance coverage, REITS, regional banks, financial savings banks, & speciality insurance coverage. FCF based mostly on trailing three years. Rebalanced quarterly. Knowledge from 1/1/1990 by 9/30/2026.
Due to rising charges, excessive leverage appears to be like to be an particularly worrying danger for small shares at current and that is more likely to be magnified by the shortage of profitability for a lot of corporations. Smaller shares, or not less than the worthwhile ones, look much less uncovered to the danger of a number of contraction posed by greater bond yields, however extra uncovered to basic pressures. One approach to measure that is to have a look at consensus estimates for curiosity expense relative to free money flows with the price of curiosity added again in (interest-adjusted free money stream). On this measure, the Russell 2000 and 2000 Worth benchmarks look notably uncovered with corporations projected to spend ~50% of their curiosity adjusted free money stream servicing their debt. Since charges have moved greater, as corporations refinance, this determine stands to maneuver considerably and will sharply cut back earnings because it does. Happily, our small technique is much much less uncovered to this danger each an indebtedness and curiosity share of free money that’s considerably much less. The comparable determine for our massive cap technique (and its benchmarks) can be proven, although debt is a a lot much less acute problem for bigger shares than for small ones.
Small cap benchmarks are enormously uncovered to the danger of rising charges with almost half their curiosity adjusted FCF dedicated to paying their debt.
Determine 19: Curiosity Expense as a Share of Curiosity Adjusted Free Money Move (NTM)

Supply: Factset, knowledge as of Oct ’26
Worldwide Technique
Worldwide shares likewise look enticing from a valuation perspective with our technique being considerably extra enticing than the benchmark (See Determine 20). And like small shares, worldwide equities have been additionally costlier than massive U.S. shares for a lot of the previous decade earlier than subsequently underperforming. Debt and money stream instability are additionally vital dangers to contemplate, however the greatest concern in our view at current is focus danger.
Worldwide shares as a bunch are cheaper than U.S. ones, however our technique is considerably cheaper than both benchmark.
Determine 20: N’TM FCF/EV Worldwide Methods

Supply: FactSet. Knowledge by 9/30/2026. FCF yield after possibility issuance.
Semiconductor and financial institution shares have surged from round a 20% weight within the ACWI Ex-U.S. benchmark 5 years in the past to almost 40% at present. This is a gigantic focus in two sectors which might be notoriously risky. For our technique, the comparable determine is a negligible 3%, as we keep away from the elemental volatility of the semi names and leverage and danger profile of the banks. This may be seen in Determine 21 which additionally reveals the identical exposures for the S&P 500 (which likewise noticed these weights improve sharply in recent times), the Russell 1000 Worth, and our U.S. FSV technique.
Worldwide benchmarks are very concentrated.
Determine 21: Financial institution & Semi /Tech Tools ACWI Ex-US Benchmark Weight Over Time

Supply: FactSet. Knowledge as of Sept ’26. Semis & Associated Tech {Hardware} consists of the next FactSet Industries: Semiconductors, Laptop Peripherals, Digital Elements, Compoter Processing {Hardware}, Digital Manufacturing Tools, Digital Tools, Laptop Communications. Banks consists of the next FactSet Industries: Funding Banks/Brokers, Regional Banks, Financial savings Banks, Monetary Conflomerates, Main Banks.
Last Phrase: Benchmark Threat
Throughout methods, our portfolios are meaningfully completely different from the benchmarks they use to report relative efficiency. That final result is a perform of the market and the main target of our work being to personal good companies that outperform over the long-term. Stated otherwise, our focus is just not about whether or not we’ll stray from a benchmark, or whether or not subsequent quarter or this yr’s outcomes will end forward or behind the benchmark, however whether or not we are able to ship to purchasers an attractively valued portfolio that gives draw back safety.
Our objective is ready in our course of, and in durations of stress we don’t stray from it. Actually, whereas we acknowledge it’s troublesome to do, taking a contrarian view is at all times essential to earn good returns and leaning in when market situations haven’t gone favorably makes extra sense than leaning in when they’re in your favor. But additionally vital, we’re fact-based traders, and stepping again and assessing our present positioning and noting the historic precedents, we consider we’re in a rare market interval and that the variations between our portfolios and their benchmarks are warranted and logical and can repay. Our concern for traders pertains to benchmarks and plenty of methods tied to them which might be taking up monumental focus and valuation danger all associated to a single theme (Determine 22).
For our purchasers, our different objective is to offer you what you must perceive our positioning and no matter you must assist you to talk that to your purchasers. In that regard, we stand prepared to assist, please attain out with any issues or questions.
Benchmarks have monumental publicity to AI.
Determine 22: AI Publicity

Supply: FactSet, knowledge as of Sept 2026. See appendix on following web page for listing of Massive 20 & Different AI shares